When the Storm Passes, the Real Fight Starts
Storm sirens go quiet, the rain stops, and Rockwall wakes up to a familiar scene. Branches in the yard, shingles in the driveway, neighbors walking the block and pointing at roof lines. A lot of people say the same thing: "Insurance will handle it."
That's where trouble often starts. Texas carriers have been tightening hail and wind coverage, raising deductibles, and drawing harder lines on what they will and won't pay for. The roof damage you see is only part of the story. The policy in your drawer decides who actually pays.
Let's walk through what storm damage roofing in Rockwall, TX usually looks like after a big one, what insurance often covers, what it doesn't, and how to protect yourself before and after you file a claim. At Apex Point Services, we're a family-owned, veteran-owned contractor here in North Texas, and we see this storm cycle repeat every year. We'd rather you be ready for the next round than surprised by it.
What Your Rockwall Roof Faces Every Storm Season
Roofs around Rockwall, Heath, and the lake communities take a beating. Spring brings hail and straight-line winds that hit roofs hard and fast. Late storms and heavy downpours push wind-driven rain under weak spots. By fall, storms roll through on already tired shingles.
Here's what your roof's up against over and over:
- Hail that bruises shingles and knocks off granules
- Strong gusts that lift or tear shingles along ridges and edges
- Wind-driven rain that finds every gap around chimneys and vents
- Heat and sun that bake shingles between storm seasons
Not every roof handles this the same way. Around Rockwall you'll see a lot of:
- 3-tab shingles, thinner and more likely to tear or crease in high wind
- Architectural shingles, thicker and better at hiding small hits but still breaking down over time
- Underlayment that may be older felt or newer synthetic, each reacting differently when exposed
- Flashing and ridge vents that take direct hail and wind on every storm
There's also a big difference between sudden storm damage and slow wear. Storm damage looks like:
- Missing or torn shingles
- Fresh hail hits with soft spots or cracks
- Wind damage along rakes and ridges
Wear and tear shows up as:
- Long-term UV damage and curling
- Granule loss in the gutters over time
- Old or improper installs that finally give out in a storm
Insurance usually pays for sudden, specific events, not a roof that simply aged out and failed on a stormy night.
What Insurance Usually Covers After a North Texas Storm
Most policies are written around "sudden and accidental" damage tied to a certain storm date. That usually means things like:
- Shingles missing or creased from wind
- Hail impacts that break the shingle surface
- Wind-driven water entry that can be linked to the storm
The typical claim path looks like this:
- You or a contractor spot damage after a storm
- A contractor documents it and you file a claim with your carrier
- An adjuster comes out, looks at the roof, and writes a scope of work
- The carrier decides if it's replacement cost or actual cash value
Replacement cost usually means they pay what it takes to put you back to similar materials, minus your deductible. Actual cash value usually means they subtract age and condition, so older roofs can get a lower payout.
For storm damage roofing in Rockwall, TX, adjusters often write up:
- Roof surface materials like shingles or underlayment where storm damage is clear
- Some flashing and vents that are obviously hit
- Sometimes gutters, if damage is severe and clearly storm-related
What they don't do is write up every single thing you wish was new. That's where a lot of frustration starts, even on valid claims.
The Storm Damage Costs Your Insurance Won't Touch
Even with a solid claim, some costs almost always land on you. The big one's your deductible. With many Texas policies, wind and hail have their own, often higher, deductible. That's money straight out of your pocket before the carrier pays a dollar.
Other common gaps include:
- Code upgrades, if your policy doesn't include ordinance and law coverage
- Pre-existing issues, tagged as "maintenance" instead of storm damage
- Old leaks or bad installs that storms exposed but didn't cause
Cosmetic vs. functional is another sticking point. Many policies won't pay for things that are "cosmetic only," like:
- Dents in metal vents that still work
- Hail dings in gutters that still drain
- Banged-up metal garage doors that still open and close
There are also all the little extras around the roof:
- Satellite dish removal and reset
- Temporary removal of holiday light hardware
- Old skylights that no longer meet current standards
- Previous DIY patches that failed in the storm
Some policies now limit coverage on older roofs, especially for wind and hail. That can mean reduced payouts or actual cash value only. On an older Rockwall or Heath roof, that can be a big difference from what you expected.
Where Homeowners Get Burned in Storm Repairs
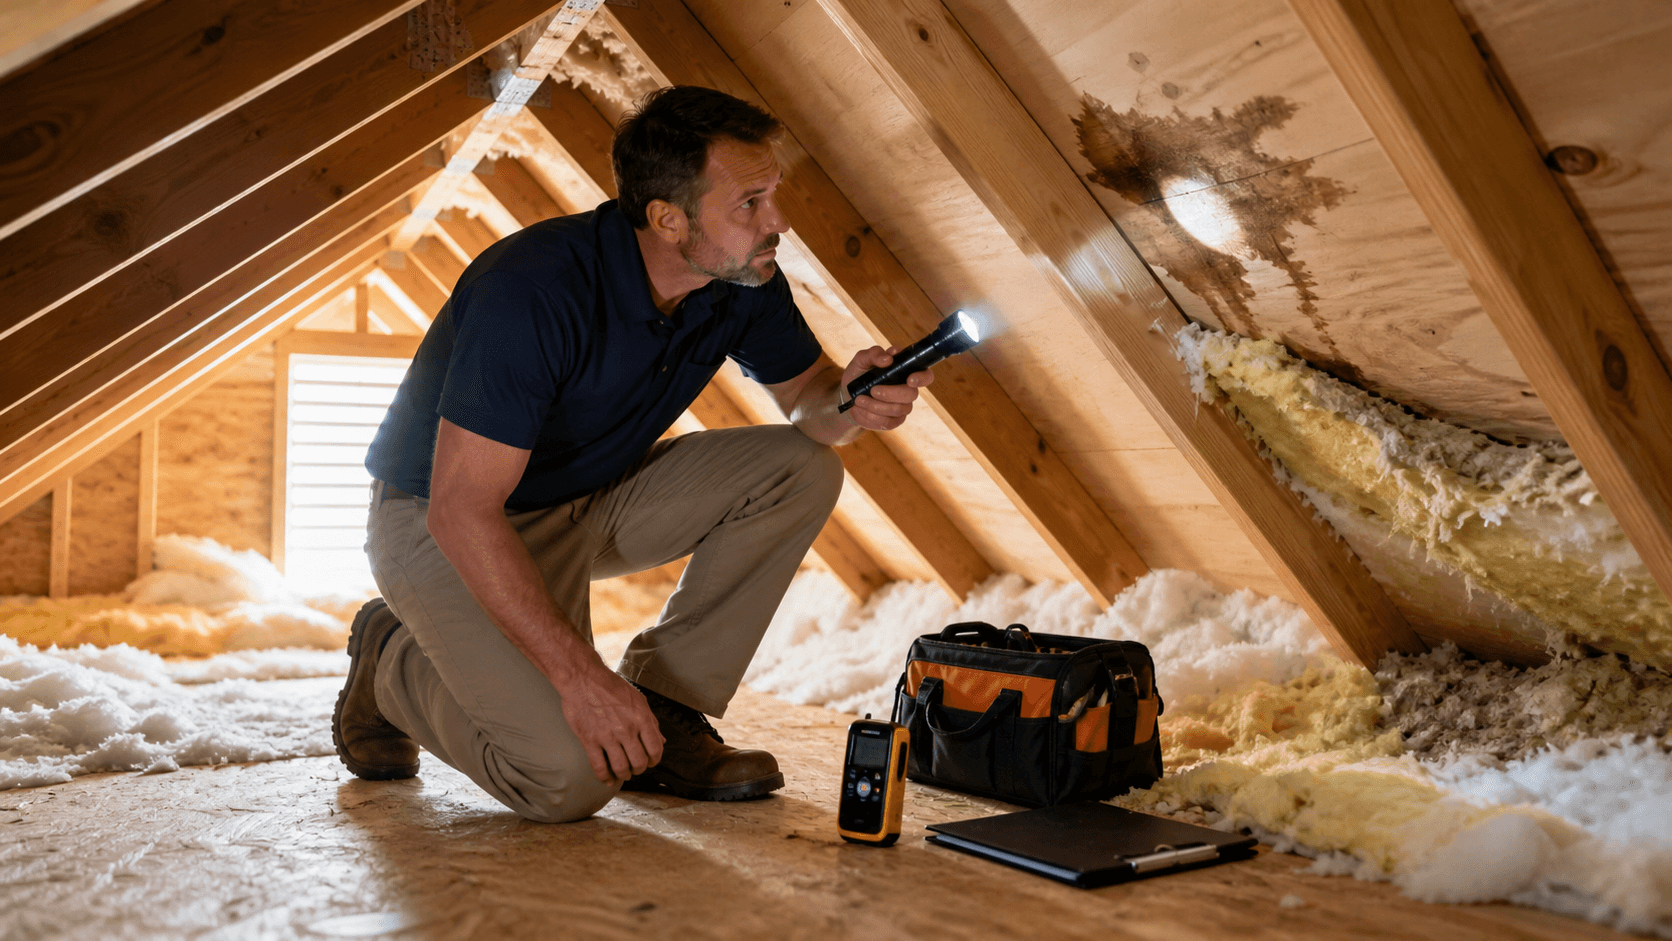
The adjuster visit isn't the end of the story. A lot of problems show up after work starts. Roofing crews pull shingles and find:
- Soft or rotten decking that won't hold nails
- Hidden flashing issues around chimneys and walls
- Old leaks that never showed inside the house
Contractors can send "supplements" to the carrier to ask for more funds when they find legitimate extra damage. Sometimes those are approved, sometimes they're not. The gap often lands on you.
Storm chasers make this worse. After a big Rockwall storm, you'll see:
- Trucks with out-of-town plates
- Promises of "free roofs" or "we pay your deductible"
- High-pressure sign-up tactics on your driveway
That "we cover your deductible" line can get you in legal or financial trouble. On top of that, insurance doesn't cover poor workmanship, shortcuts, or unpermitted changes. If a bad job leads to new leaks next year, that's not a storm claim. Who you hire matters as much as what your policy says.
How Apex Point Services Helps You Plan for the Gaps
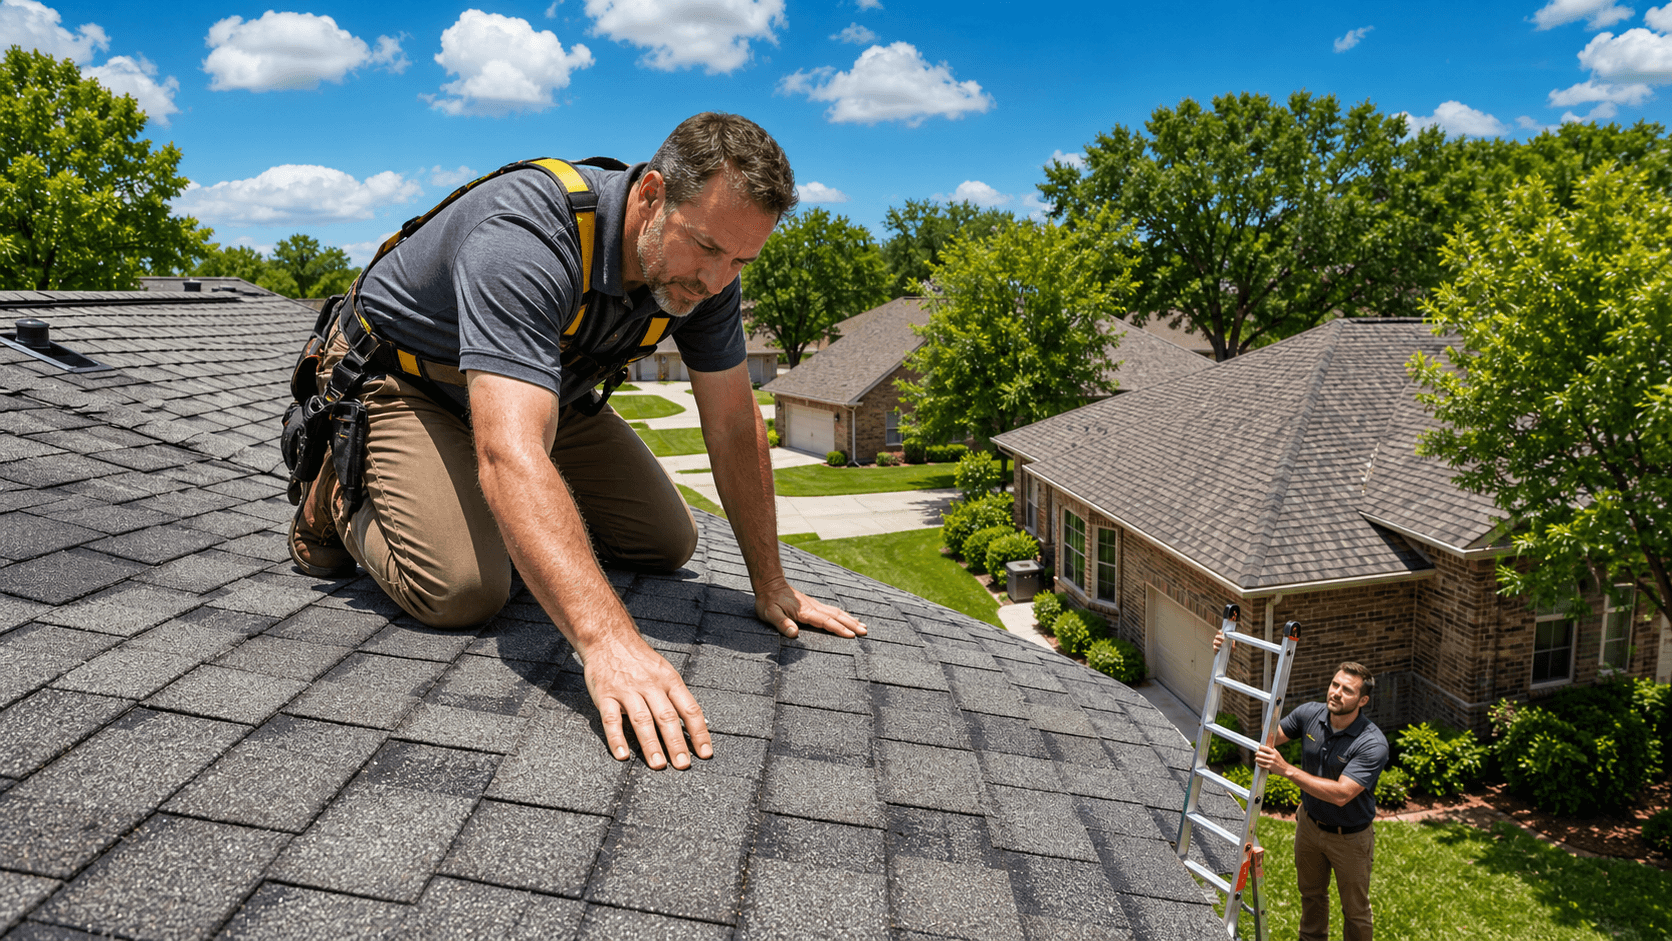
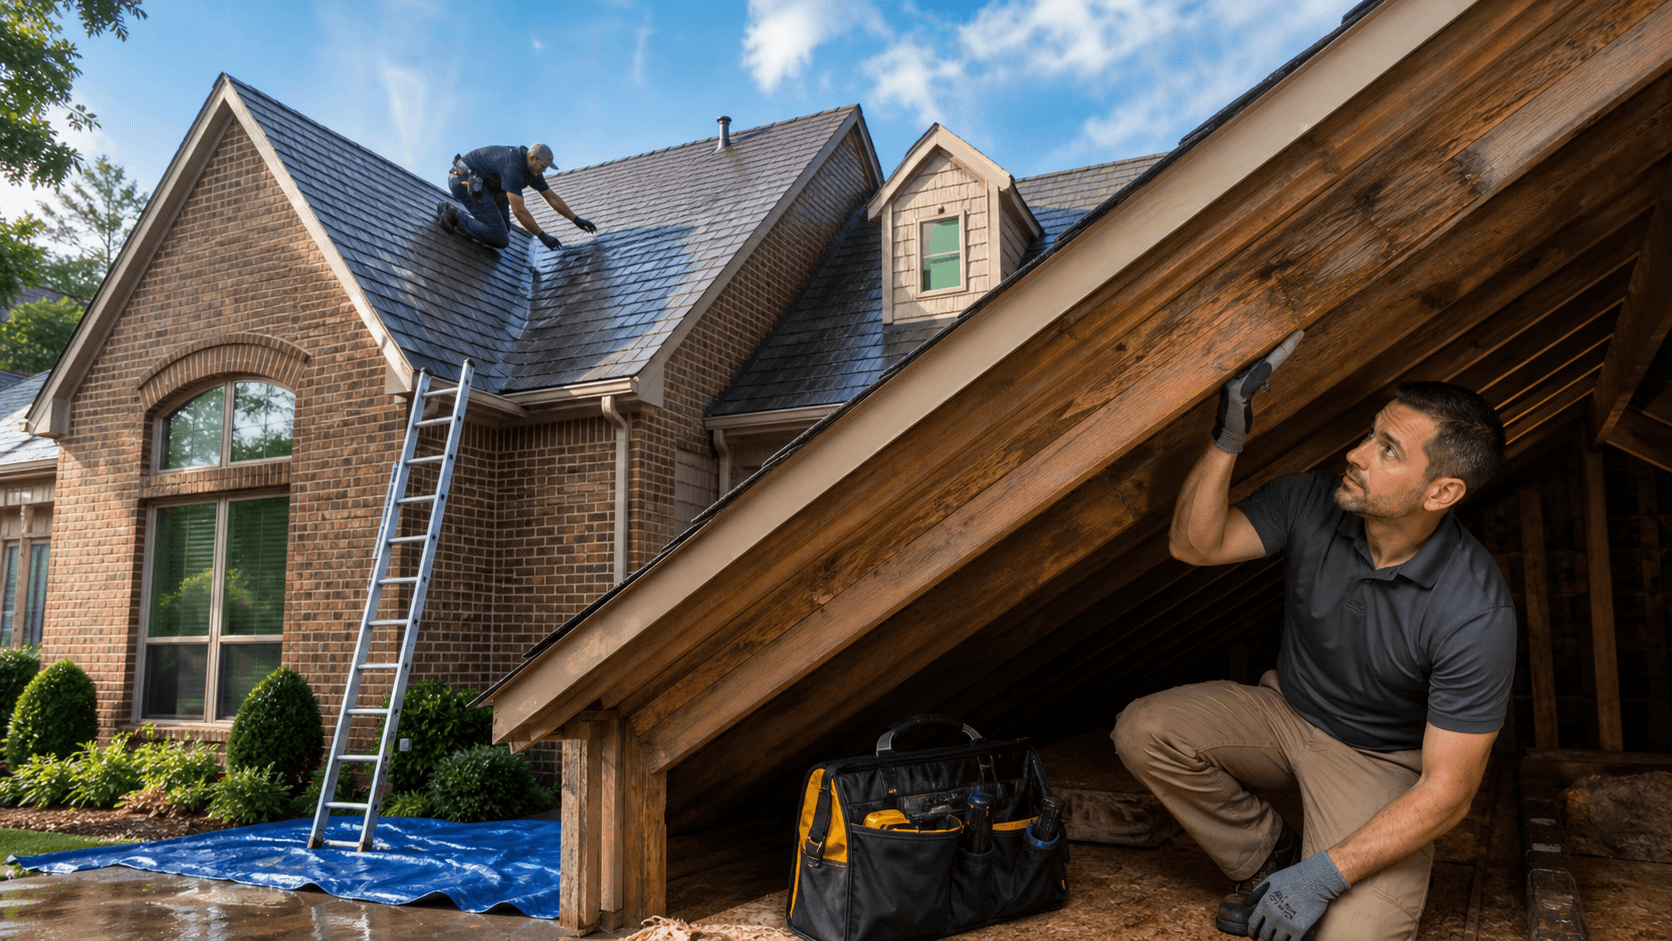
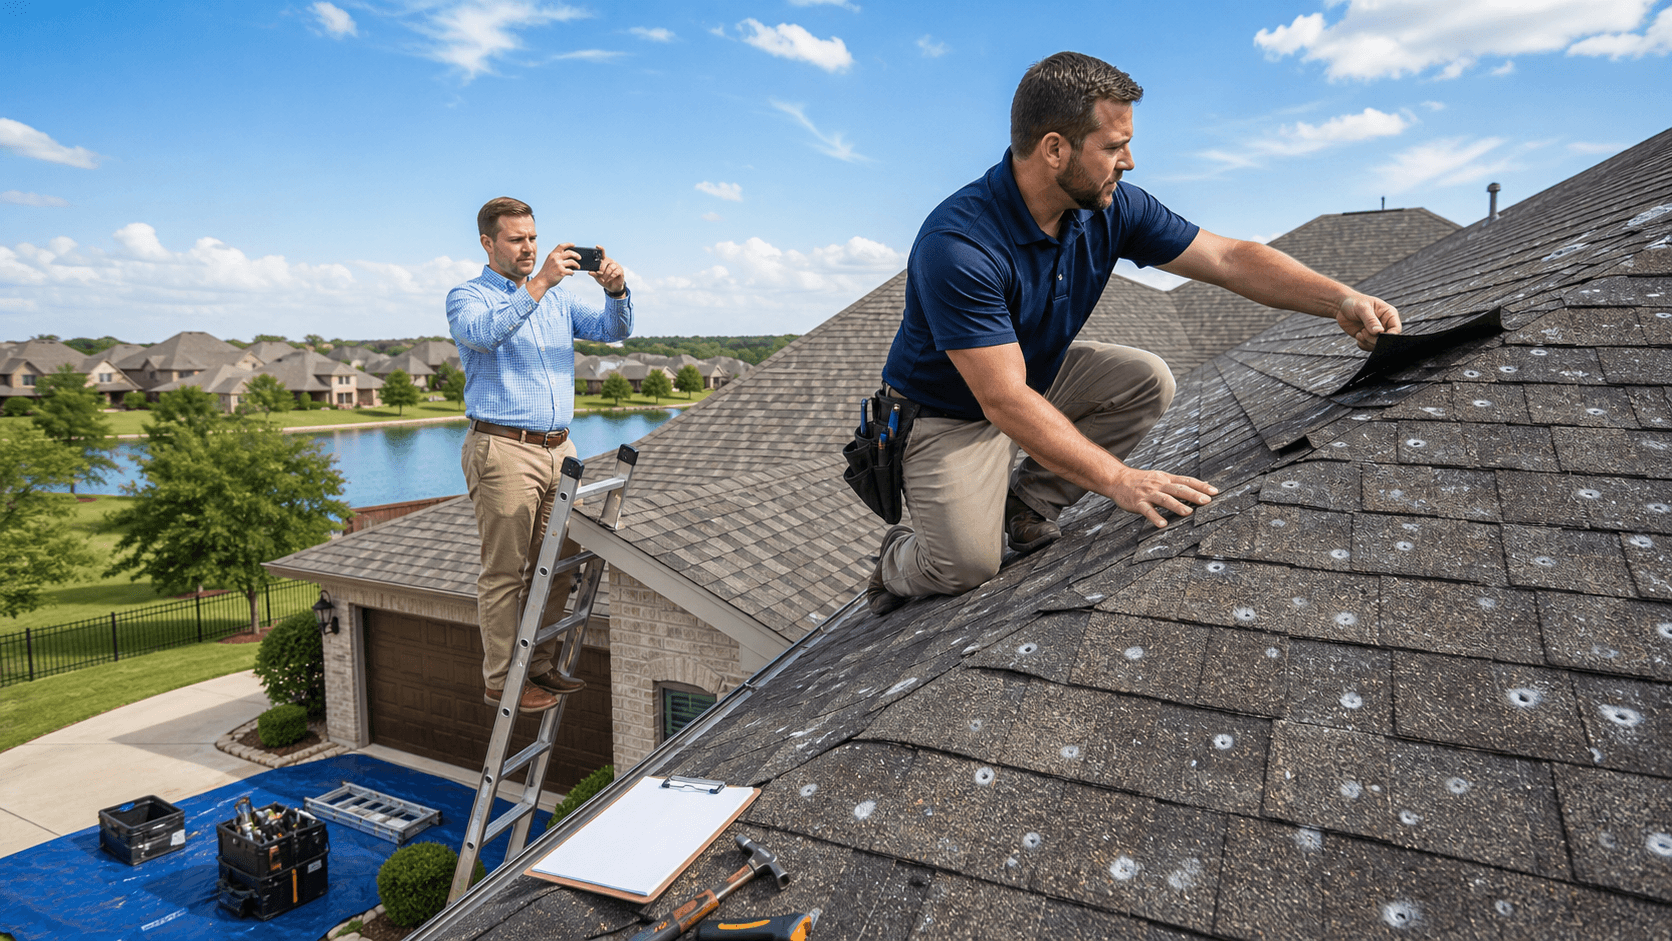
This is where a careful, local contractor makes a difference. Before any claim, we like to start with a detailed roof inspection and clear photos. We draw a hard line between true storm damage and old problems so you know what you're dealing with.
Here's how we handle storm damage roofing in Rockwall, TX:
- Walk the roof and exterior, document damage, and explain it in plain language
- Talk through what looks storm-related and what looks like age or maintenance
- Help you understand what items are likely covered and what may fall on you
When it's time for the job, we plan it for real Texas weather. That means:
- Materials that handle hail, heat, and wind
- Realistic timelines based on your roof size and complexity
- Clear bids so you know what's included and what counts as extra work
If we find surprises like rotten decking or hidden leaks, we bring them to you fast and explain your options. On the insurance side, when homeowners ask, we can be on-site for adjuster visits, help explain the roof, and flag items we believe should be looked at again. We don't promise the carrier will say yes, but we stand on what we see.
Accountability matters to us. We show up when we say we will, protect your yard and driveway while we work, keep you updated on changes, and stand behind our workmanship long after the storm crews leave your street.
Get Your Roof Checked Before the Next North Texas Storm
Fall in Rockwall is a smart time to get ahead of the next round of hail and wind. Fixing known issues now gives the insurance company less room to call future damage "old" or "maintenance." It also means the next big storm's hitting a roof that's actually ready for it.
A simple roof and exterior check from a local team like Apex Point Services can show you what your roof can likely handle and where you might be exposed. If you'd like a straightforward look at your roof before the next storm season, reach out and we'll walk it with you, no pressure and no scare tactics.
Get Started With Your Project Today
If your home has been hit by severe weather, our team at Apex Point Services is ready to inspect your roof, explain your options, and restore your peace of mind. Learn how our specialized storm damage roofing in Rockwall, TX can protect your home before the next storm rolls through. Reach out today and we will walk you through every step, from assessment to repair. If you are ready to schedule an appointment or have questions, simply contact us.